
[ad_1]
- Canadians’ pandemic savings are still growing to about $350 billion as of Q3 2022.
- But those savings remain unevenly distributed, with higher incomes taking the lion’s share.
- Rising inflation and debt servicing have already eroded the more modest savings of lower-income households. That is expected to continue as they borrow more to pay for essentials.
- it comes down to: With a looming recession, the asymmetry of savings will lead to a more dramatic period of pain for lower-income Canadians. While the savings stock of high-income earners is unlikely to be spent, lower-income households will continue to be squeezed by higher living costs.
The vast treasure trove of pandemic savings is still intact
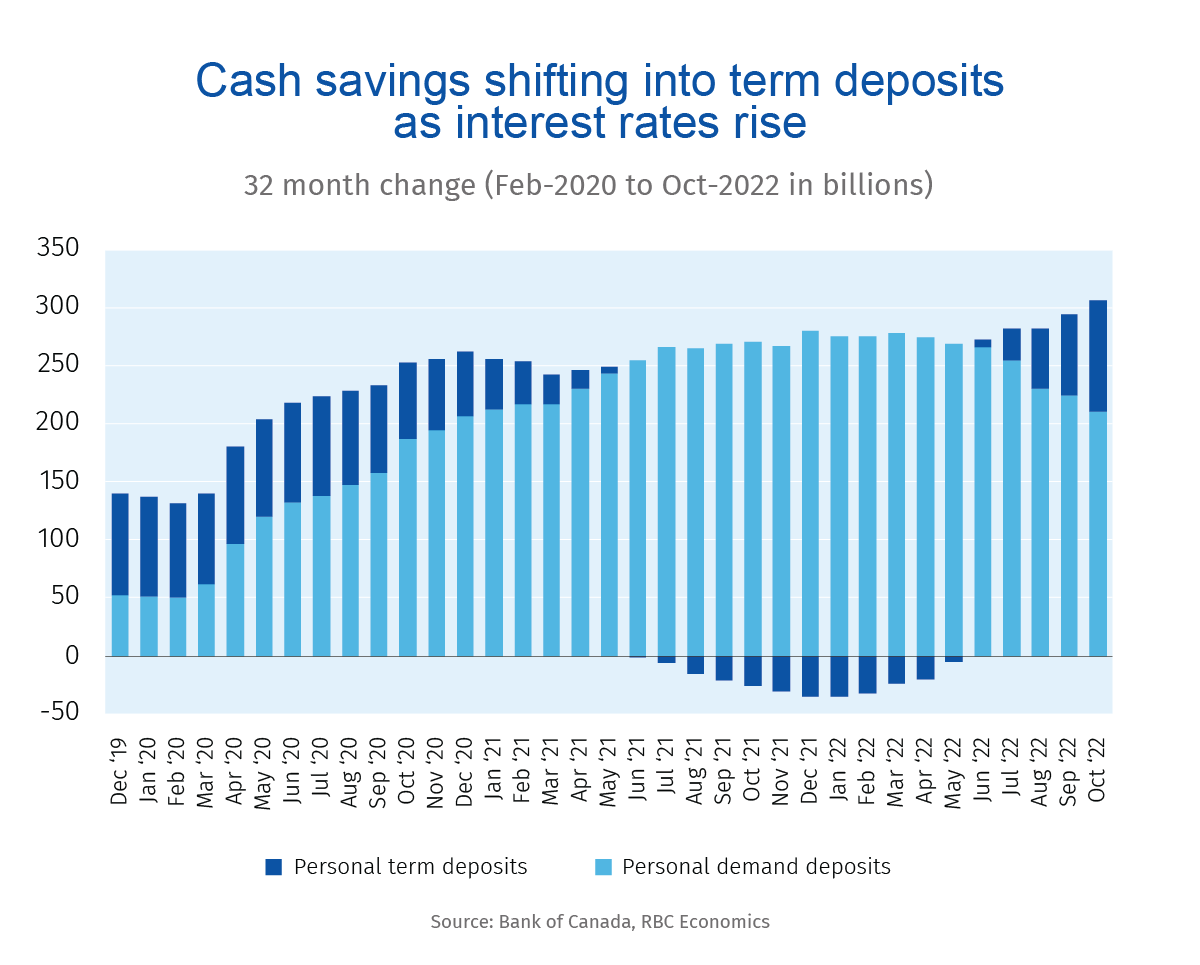
In previous work, we found that Canadians had accumulated record savings during the COVID-19 crisis. Thanks to a combination of government support and reduced spending options, household savings rose by about $350 billion above pre-pandemic levels by the end of the third quarter of 2022.
That pace slowed as government handover programs faded and pandemic restrictions eased. But the pile of excess savings has yet to get smaller. Demand deposits at chartered banks (which allow instant withdrawals) are starting to decline. But instead of flowing into consumer spending, this money has shifted into time deposits (which lock money in for longer terms, but yield higher returns because of higher interest rates).
That means the post-lockdown recovery in Canadian household spending has been funded entirely from earned income. This was facilitated by a rapid recovery in labor markets in the first half of the year, offsetting the reduction in government support.
The rising cost of living widened the savings gap
The cost of living for Canadian households will continue to rise. A fall in inflation only means that prices will grow more slowly. And the delayed effect of interest rate hikes in 2022 will continue to drive up the cost of household debt servicing, adding pressure to household finances. Our current projection is that debt payments will rise to a record 16% of household disposable income by the end of 2023, leaving less income to spend.
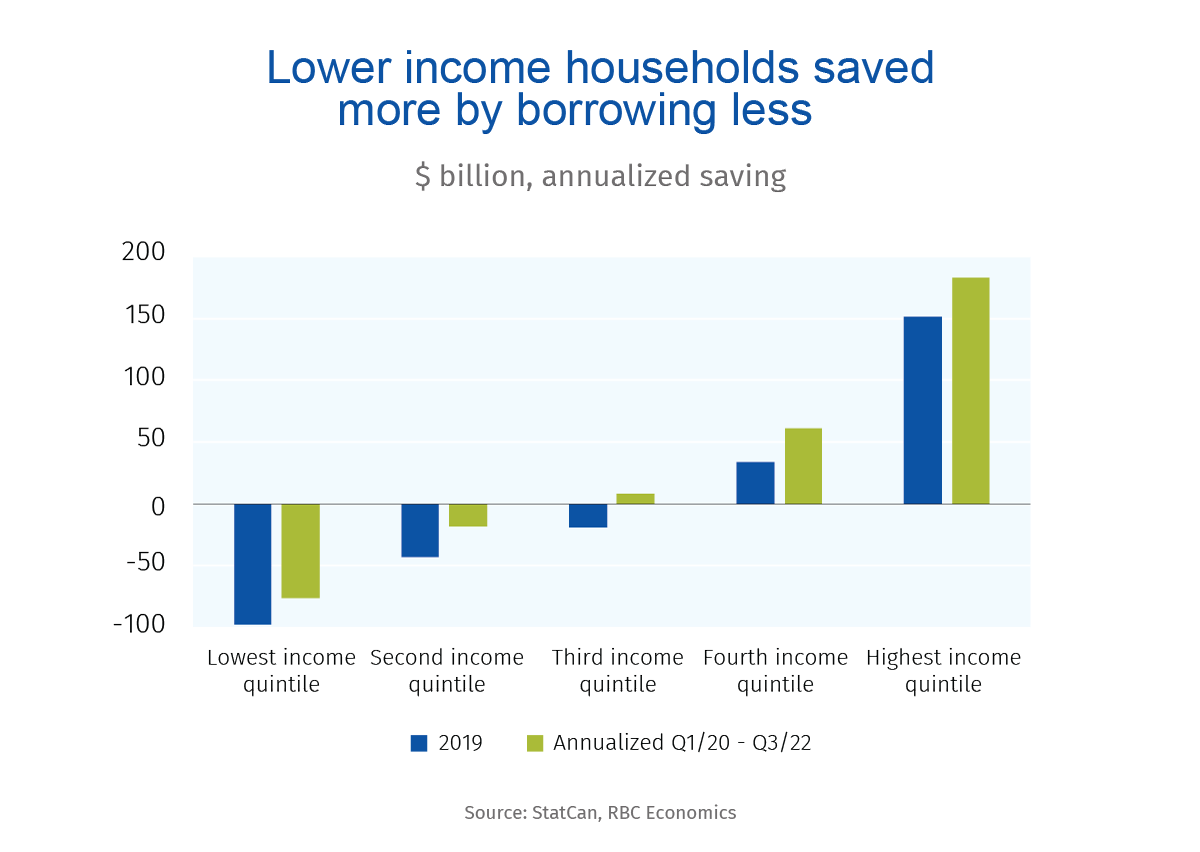
This dynamic will take the heaviest toll on lower-income households, those with the smallest savings reserves. Instead of saving more during the pandemic, lower-income households actually just borrowed less. According to Statistics Canada, average household savings among the bottom 40% of income earners were already negative in the first quarter of 2020. They fell another 12% below that level in the third quarter of 2022 as the cost of living rose. By way of comparison, savings increased by 28% in the same period among the 40% with the highest incomes.
These higher-earning households will probably continue to save. Rising interest rates, a sharp fall in house prices and lower asset values in the financial markets have eroded consumer confidence. And lower consumer confidence usually leads to Lake save, not less. As we noted in previous work, household net worth, which peaked during the pandemic, is now shifting from a driver to a drag on spending growth. More than $1 trillion in assets were wiped out in the second and third quarters of last year as the housing and financial markets retreated. And while net worth is still ahead of pre-pandemic levels, these factors have left Canadians feeling much less prosperous.
High savings cannot prevent a recession
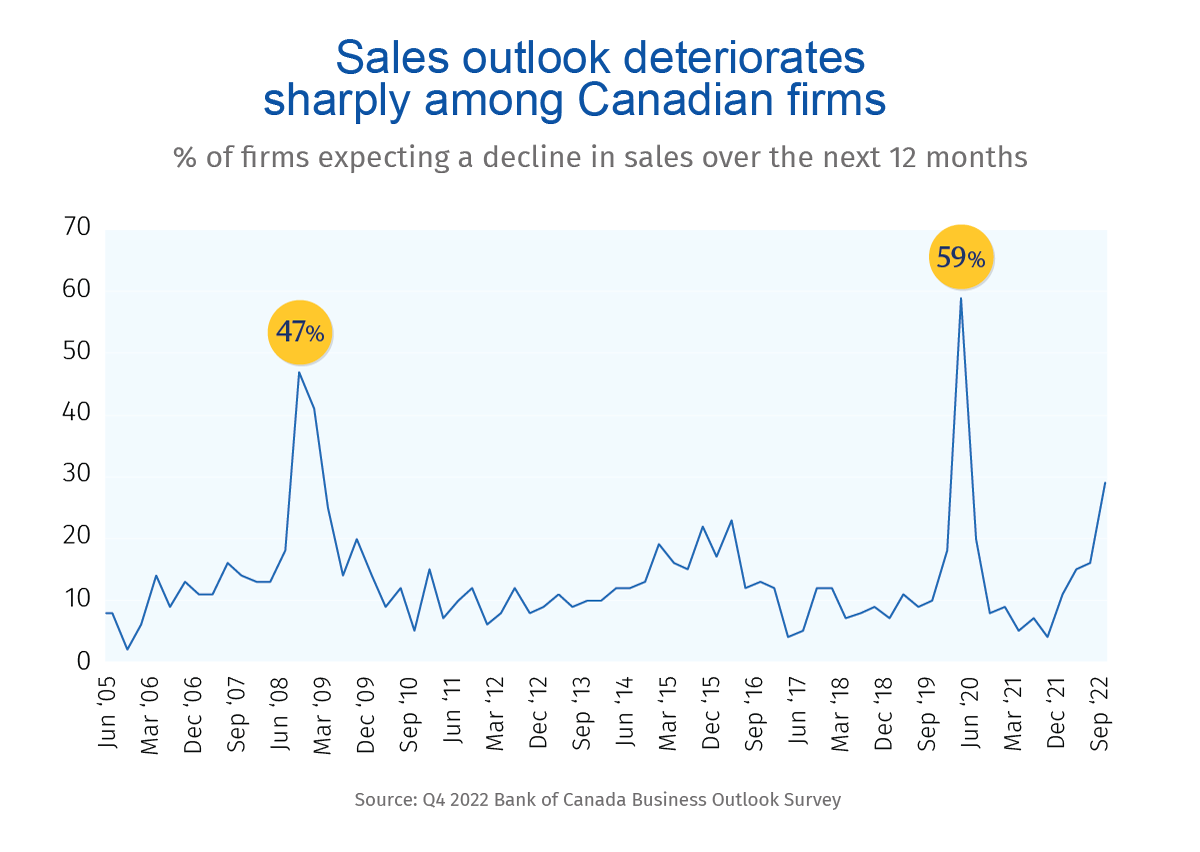
We still expect a moderate recession in the first half of 2023 as central bank rate hikes cool an overheated economy. The Bank of Canada’s latest Business Outlook Survey has already shown signs of a deterioration in consumer demand. And the survey found that companies expect an outright decline in future sales, with companies tied to housing or consumer spending bracing for the biggest impact.
Savings among high-income households are big enough — the equivalent of 4.5 years of pre-pandemic spending on food and restaurants — that consumer spending could prove more resilient than expected. But another surge in spending on discretionary purchases would likely also lead to higher inflation and interest rates and possibly a bigger recession down the road. For lower-income Canadians, much smaller savings buffers could mean a much more challenging year.
Nathan Janzen is assistant chief economist and heads the macroeconomic analysis group. His focus is on analyzing and forecasting macroeconomic developments in Canada and the United States.
Claire Fan is an economist at RBC. She focuses on macroeconomic trends and is responsible for projecting key indicators for GDP, labor markets and inflation for both Canada and the US.
Proof Point is edited by Edited by Naomi Powell, Editor-in-Chief of RBC Economics & Thought Leadership.
This article is provided for general information only and should not be considered legal, financial or other professional advice. A professional adviser should be consulted about your specific situation. The information presented is believed to be factual and up-to-date, but we cannot guarantee its accuracy and should not be taken as a complete analysis of the topics discussed. All expressions reflect the authors’ judgment as of the date of publication and are subject to change. No endorsement of any third party or their advice, opinions, information, products or services is expressly given or implied by Royal Bank of Canada or any of its affiliates.
|
Sources 2/ https://thoughtleadership.rbc.com/proof-point-canadians-are-still-clinging-to-pandemic-savings/ The mention sources can contact us to remove/changing this article |
[ad_2]