
[ad_1]
Even as Microsoft gave MSFT a cautionary picture about its core cloud business and overall revenue with its latest quarterly results, the software giant continued to post solid results.
The tech giant noted that customers are wary in the current uncertain economic environment and focused on optimizing their spending. That serves to put a cap on key growth companies, especially Azure, Microsoft’s cloud computing platform.
Bulls may highlight Microsoft’s good growth in residual performance obligation and Azure, while bears may point to slowing revenue growth and a light outlook, writes Dan Romanoff, senior equity analyst at Morningstar.
We view the results as strengthening our long-term position focused on the proliferation of hybrid cloud environments and Azure as the company continues to leverage its on-premises dominance to enable customers to move to the cloud at their own pace, says Romanoff .
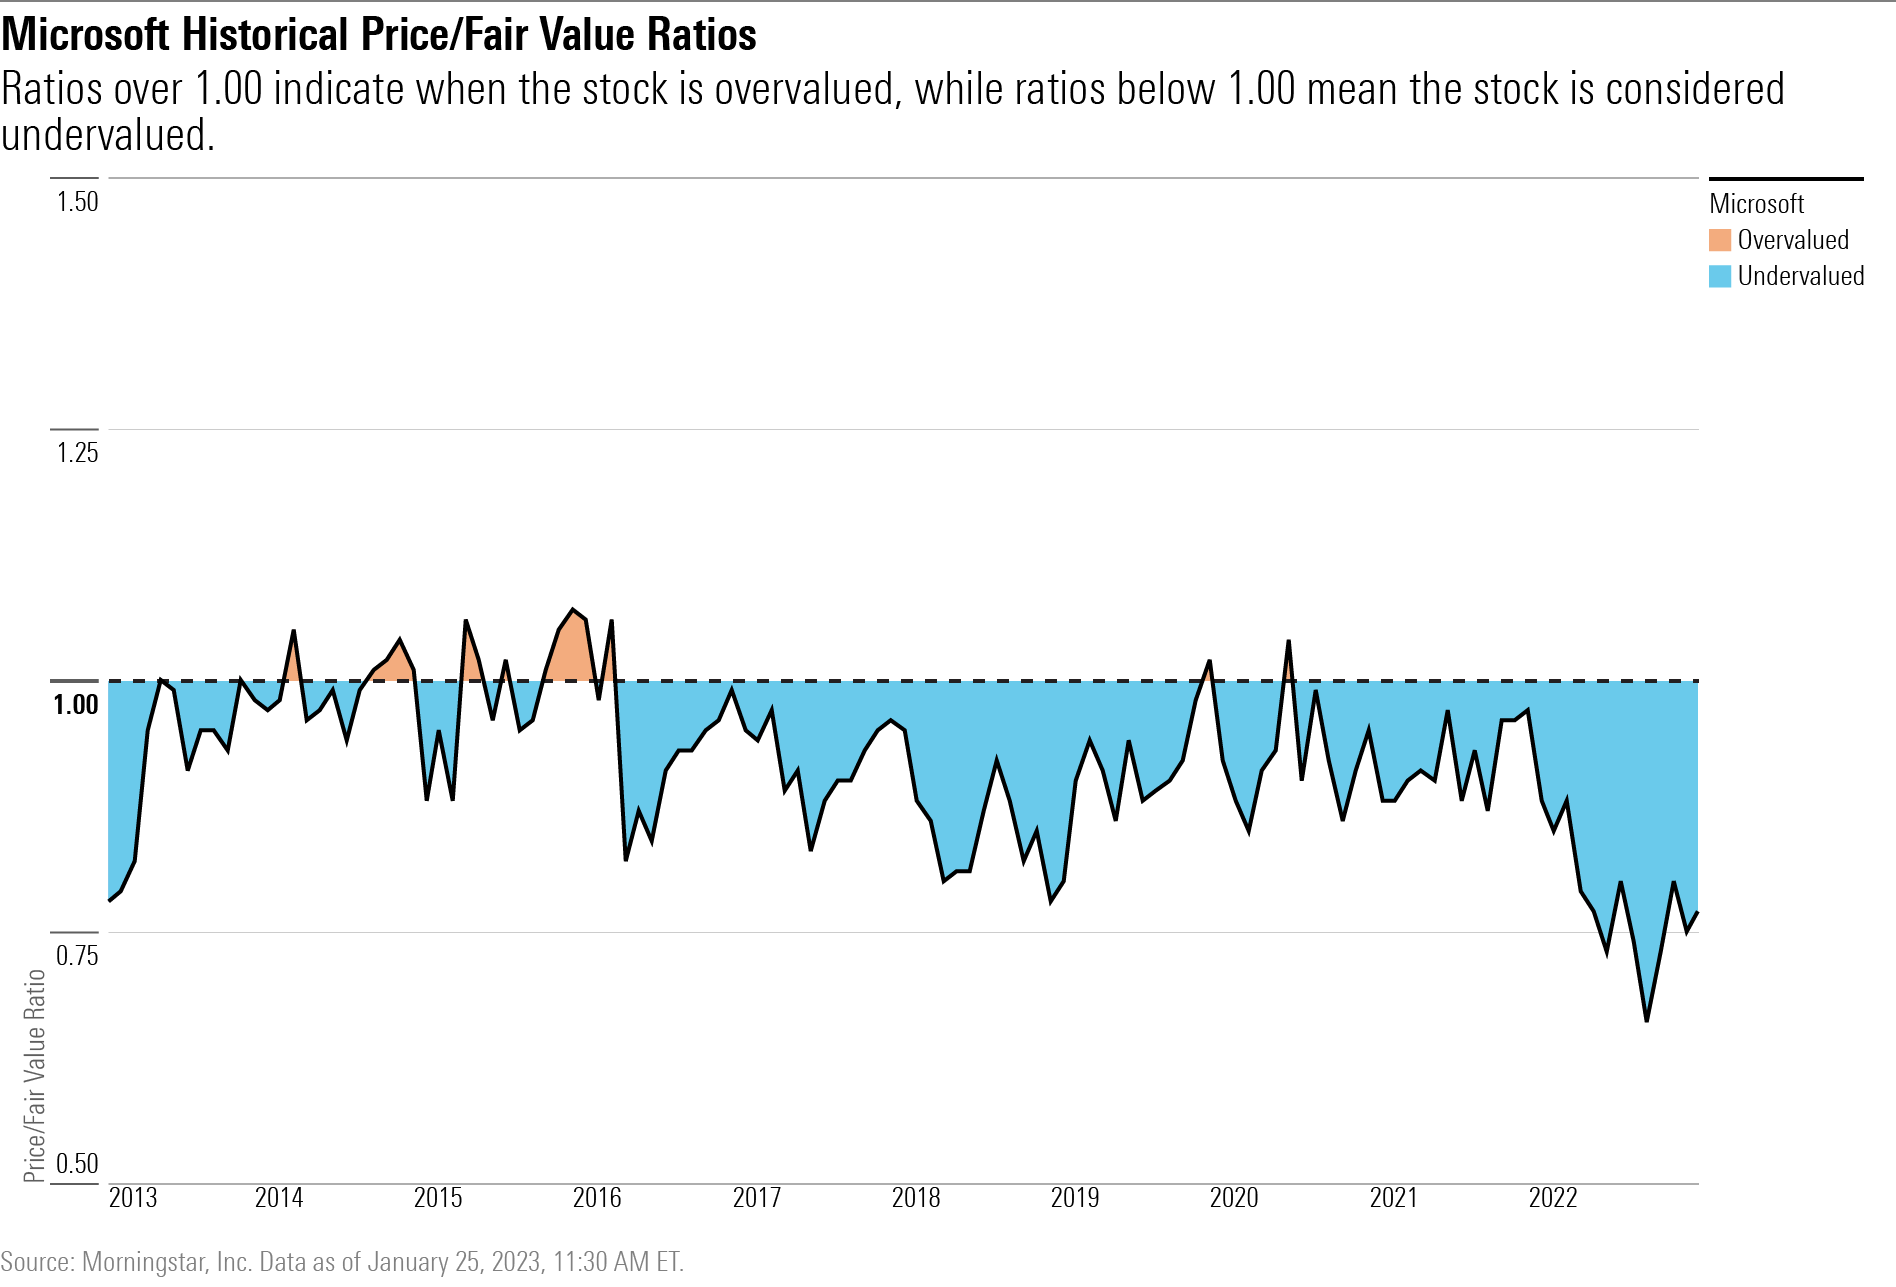
Still, given the company’s outlook, Romanoff lowered his estimate of the fair value of Microsoft stock from $320 per share to $310. With a share trading around $240, Microsoft is undervalued, with a valuation of 4 stars. We continue to find equities attractive, he writes.
Microsoft Key Earnings Takeaways
- Revenue: $52.75 billion versus Factsets mean $52.97 billion estimates.
- Profit per share: $2.32 versus median estimates of $2.29.
- Weaknesses in Windows, advertising and gaming, which underperformed than expected and are likely to continue to slow and be under more pressure than Microsoft’s enterprise software companies.
- Revenue guidance for the third quarter was lower than expected, between $50.50 billion and $51.50 billion, versus the consensus of $52.51 billion.
- Microsoft is expanding into artificial intelligence, reportedly investing $10 billion for a 49% stake in OpenAI, potentially a new path to long-term growth.
Microsoft reported revenue of approximately $52.75 billion for the second quarter of fiscal 2023, which aligns with the midpoint of the company’s $52.85 billion expectation. Turnover was down 2% compared to a year ago.
While results were solid, driven by better-than-expected growth in Azure, Microsoft’s cloud computing platform, key near-term revenue concerns remain.
Currency headwinds continue for software stocks
Currency remains a major headwind, as the company reports that the decline in sales would have been about 7% in constant currency, a 5 percentage point difference. Currency, in general, has been a major concern for software companies. While a strengthening U.S. dollar is normal in times of global macroeconomic turmoil, this is one of the worst currency situations we’ve seen in the past 25 years, writes Romanoff.
US software companies covered by Morningstar analysts have an average of 43% of their revenue from abroad. As of June 30, 2022, Microsoft derives approximately 49.5% of its revenue from outside the US, according to PitchBook Data. Management expects a currency headwind of approximately 300 basis points for the quarter ending in March.
Microsoft sees growth slowdown across the board
Microsoft’s Intelligent Cloud segment revenue was up 18% overall, driven by growth in Azure, the company’s cloud computing platform, which grew 31% year-over-year, or 38% at constant exchange rates.
We were pleased with the strong year-over-year (in constant currency) growth in Azure at 38% and Dynamics 365 at 29%, as both are important pillars of our long-term growth projections, writes Romanoff.
Growth in Azure, a key pillar of Romanoff’s Microsoft thesis, slowed from the previous quarter, when it grew 35%, or 42% on a constant currency basis.
Chief executive officer Satya Nadella pointed to companies turning away from the acceleration seen during the coronavirus pandemic in adopting cloud technologies. What customers do is what they accelerated during the pandemic: they make sure they get [the] getting the most value out of it or optimizing it, he said during the company’s conference call with equity analysts. And then also be a bit more cautious given the macroeconomic headwinds that there is in the market.
Microsoft has also shifted to focus on helping customers meet their goals in optimizing spend on Microsoft services, a move that Nadella says should help retain customer loyalty and reinvigorate spend. to blow once macroeconomic pressures ease.
This is an important time for Microsoft to work with our customers, help them get more value from their tech spend and build long-term loyalty and share position, while internally aligning our own cost structure with our revenue growth, he said.
Weakness in Windows, devices and gaming
The weakest link in Microsoft’s results was its Windows, devices and gaming businesses, which saw significant year-over-year declines that Romanoff said were worse than expected. Windows software and device sales both fell about 39%. Xbox content and services fell 12%.
Weak consumer-related revenues from Windows, advertising and gaming continue to be more pressured than enterprise software in the near term, he says. Romanoff believes most of the recently announced layoffs are likely to target these areas.
On the outlook, we continue to focus our growth assumptions on Azure, Office E5 migration and traction with the Power platform for long-term value creation. That said, we continue to believe results will remain subdued for several quarters to come, Romanoff writes.
Key takeaways from Microsoft Stock
- Industry: Technology
- Industry: Software Infrastructure
- Fair Value Estimate: $310
- Morningstar rating: 4 stars
- Assessment of economic moat: broad
- Moat trend: stable
Microsoft ramps up artificial intelligence push
In a recent post on the company’s blog, Microsoft revealed it was strengthening its partnership with OpenAI, the maker of popular artificial intelligence software ChatGPT. Azure is now the exclusive cloud provider for the technology. The company also now reportedly owns about a 49% stake in OpenAI after a $10 billion investment, which Romanoff says immediately makes Microsoft an AI leader.
We view the opportunities to make money immediately as limited, but believe they will become more important over time as customers become more comfortable using and interacting with AI, and the use cases increase. We see Microsoft’s solutions as ultimately more attractive with advanced AI capabilities, which we believe drive further adoption and perhaps higher prices as well as entirely new solutions, he says.
|
Sources 2/ https://www.morningstar.com/articles/1133373/microsoft-earnings-results-solid-despite-caution-on-revenue-cloud-business The mention sources can contact us to remove/changing this article |
[ad_2]