
[ad_1]
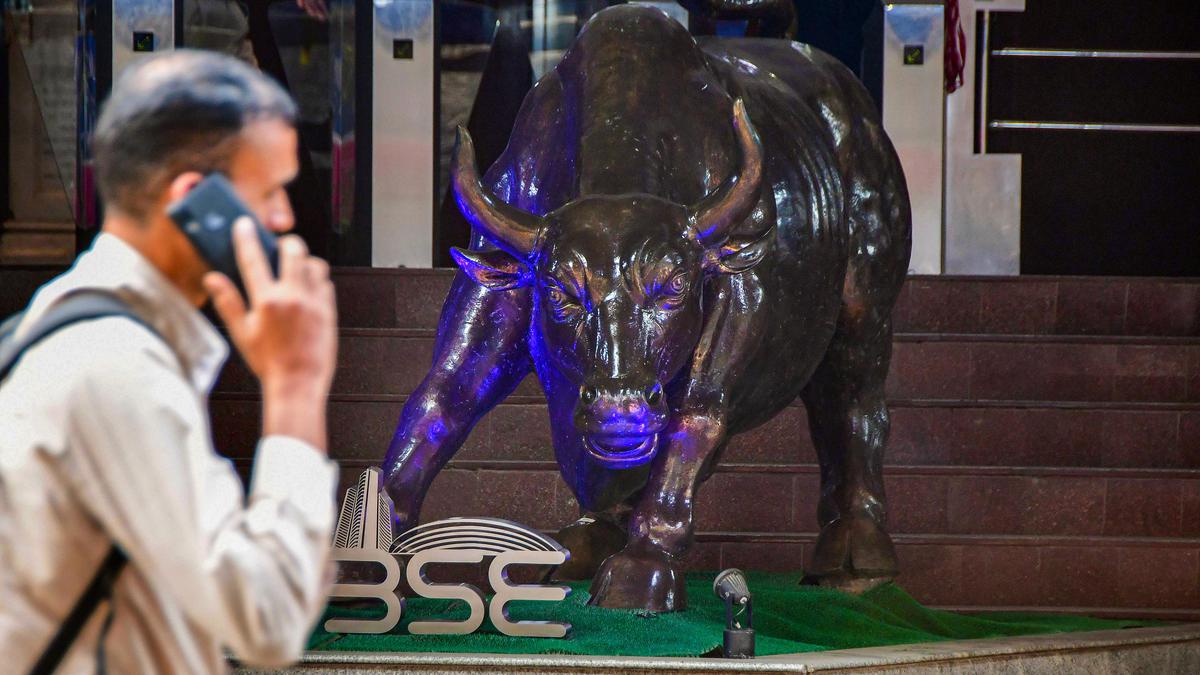
A pedestrian walks past the Bombay Stock Exchange (BSE) building in Mumbai on January 27, 2023. | Photo credit: PTI
The story so far: On January 27, equity markets in India completed the transition to the T+1 settlement regime. It has become the second largest market after China to make the transition ahead of the US, Europe and Japan, which adhere to the T+2 settlement cycle. The phased transition had begun on February 25 last year following market surveillance The Securities and Exchange Board of India (SEBI) circular in September 2021.
What is the T+1 settlement cycle about?
A transaction involves three major functions, trade execution, clearing and settlement, performed by separate entities. The clearing function means that the involved entity determines the obligation of what must be delivered and what must be received by the parties involved. At this stage, a risk assessment of both parties takes place. The process ensures that the parties have enough money or transferable assets to allow the transaction to go through. On the settlement date, funds and securities are transferred to their new owners. All this is preceded by the purchase or sale of a share. It is represented using T, that is, trades executed on a given day. Since clearing used to be the next day followed by another day for settlement, the previous mechanism was defined as T+2. From now on, the settlement will be done the next day itself, so T+1.
About the infrastructural changes that have been made for the transition, the Bombay Stock Exchange (BSE) said. The HinduOn our side, we have kept our infrastructure ready to handle additional activities in the T+1 settlement cycle, including updating securities settlement data, real-time monitoring systems, margin calculation, settlement activities, etc., within the shortened time cycles. The exchange said it observed no gaps and all processes were managed smoothly.
In a digital age, why is there no immediate settlement?
The process is complex and many parties are involved. Founder and CEO of brokerage firm Zerodha, Nithin Kamath, had stated in a post: While instant settlement is impossible, even T+0 is extremely difficult given the time it takes brokers to crystallize the liabilities and then free up companies to settle. It is important to note that an investor cannot directly buy or sell shares on an exchange. Registered members of a stock exchange, called stockbrokers, act on behalf of an investor. While individuals can open a demat account themselves by contacting a Depot Participant (DP), they need a trading account, which is provided by a SEBI-registered broker, to buy or sell stocks. The size and operating ability of the individual broker is another important factor.
What is the debate around the T+1 regime?
Global investment associations including Asia Securities Industry & Financial Markets Association, Asia Trader Forum and The Investment Association (IA) had noted in a joint open letter (in September 2021) that the transition would require an end-to-end process redesign and substantial investment in technology and enhancements to support near real-time processing capabilities and require a longer migration timeline. It added that this would especially apply to foreign investors (such as those in the US and Europe) for participation in the Indian market due to time zone differences and involvement of multiple parties (such as global and local custodians, FX banks and brokers). ) in different jurisdictions.
Milan Vaishnav, founder of Chartwizard FZE and Gemstone Equity Research, told The Hindu: What has happened so far is that it would take some time to allocate the trade to the client, which should now be faster, adding : The time zone difference would also cause problems, but eventually they will align. The US Securities and Exchange Commission (SEC) had also argued in its proposal (February 2022) that the more days that elapse between the execution of a trade and the default of a counterparty, the greater the variance of the price change would be. In other words, the asset price is likely to deviate from the execution price. According to Mr. Vaishnav, the rotation of money would become faster from an investor’s point of view. You also keep fewer margins with the broker, obligations are one day shorter and receipts also arrive one day earlier than before. All in all, this would lead to some reduction in the overall margin requirements of the retail investor or trader. For brokers, Mr. Vaishnav that it would reduce the amount of margin they hold with clearinghouses because the settlements would be faster.
|
Sources 2/ https://www.thehindu.com/business/markets/explained-how-will-the-t1-settlement-cycle-impact-markets/article66444309.ece The mention sources can contact us to remove/changing this article |
[ad_2]