
[ad_1]
Russia’s war against Ukraine has both reduced gas supplies to the EU and created risks for future supplies. The amount of gas supplied to the EU from Russia fell to an all-time low at the end of 2022, reaching about 20% of its pre-war level. The decline in Russian gas exports to the EU started before the war, resulting in low gas storage levels as early as early 2022. the accumulation of gas in storage in the summer of 2022. Such measures provided some certainty about the security of gas supply for this winter, provided that the weather does not become too severe. However, the EU could face greater challenges in replenishing gas storage levels ahead of the winter of 2023-24. Particularly as gas supplies from Russia have dwindled, the EU has had to turn to global LNG markets. While this has alleviated immediate supply problems, it has made gas supplies and prices in the EU more sensitive to fluctuations in energy demand from the rest of the world, in particular from China. This box analyzes the potential global risks to the EU’s gas supply in 2023 due to shifts in Russian supply and Chinese gas demand in a historically tight global gas market.
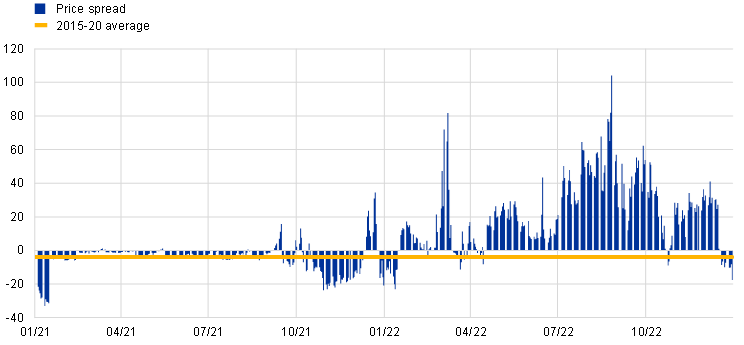
With supplies from Russia declining, the EU is turning to global LNG markets. As a result, the gas markets of the EU and Asia have become increasingly intertwined. Historically, gas prices in Asia have traded more expensively than in the EU. This is because Asia is more dependent on LNG to cope with fluctuations in gas demand, while the EU has access to cheaper pipeline gas, mainly from Russia (Chart A, panel a). This situation changed after Russia cut off pipeline supplies to the EU and imposed an unprecedented tightness on the EU gas market. As a replacement for Russian gas, demand for LNG from the EU has increased over the past two years. As a result, the correlation between gas prices in the EU and Asia has increased significantly. This is because buyers in the EU compete with Asian buyers and therefore have to pay a premium to Asian prices to attract the LNG cargoes needed (Chart A, panel b). The correlation between gas prices in the EU and gas prices in the United States has increased to a lesser extent, as the country produces most of the natural gas it consumes.
Chart A
Spread between gas prices in the EU and Asia and correlations between gas prices
a) Spread between gas prices in the EU and Asia
(EUR/MWh)
b) Correlations of prices in Asia and the US with changes in gas prices in the EU
(correlation coefficient)
Sources: Bloomberg and ECB staff calculations.
Explanation: Panel a) shows the spread between TTF and JKM month-ahead prices. Panel b) shows the correlations between the TTF and the JKM/Henry Hub daily changes in the month-ahead prices.
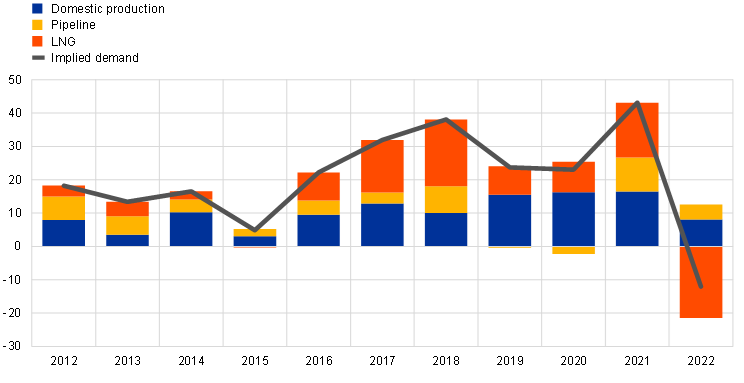
A rebound in Chinese LNG imports could limit the EU’s ability to secure gas supplies in 2023. Increased gas imports into the EU in 2022 were partly made possible by paying higher gas prices, but also by a significant drop in Chinese demand for LNG. Demand for LNG in China in 2022 was 22 billion cubic meters (bcm) lower than in 2021 (Chart B, panel a). In addition to lower consumption in other countries and an expansion of global LNG export capacity, mainly in the United States, the EU was able to import significantly more LNG than in the previous year (Chart B, panel b). The decline in Chinese LNG imports in 2022 interrupted a decade of rising Chinese demand for gas. In part, the drop in gas consumption may reflect China’s decision to switch to more coal-fired power generation over energy security concerns. However, the main driver was lower gas consumption in the industrial sector[1]which was severely affected by the 2022 lockdowns. Due to China’s departure from its zero-COVID policy in late 2022, the increased economic activity is likely to spur a rebound in demand for LNG, significantly lowering the global LNG market pressure, which is unlikely to see major expansions in export capacity until 2025.[2] This could limit the EU’s ability to attract LNG imports, especially as China has the right to decide whether to purchase a pre-agreed amount of LNG gas, which represents a significant portion of global LNG cargoes.[3]
Chart B
Changes in gas demand in China and global LNG imports
a) Annual changes in Chinese gas demand
(bcm)
b) Annual changes in global LNG imports
(bcm)
Sources: Bloomberg and ECB staff calculations.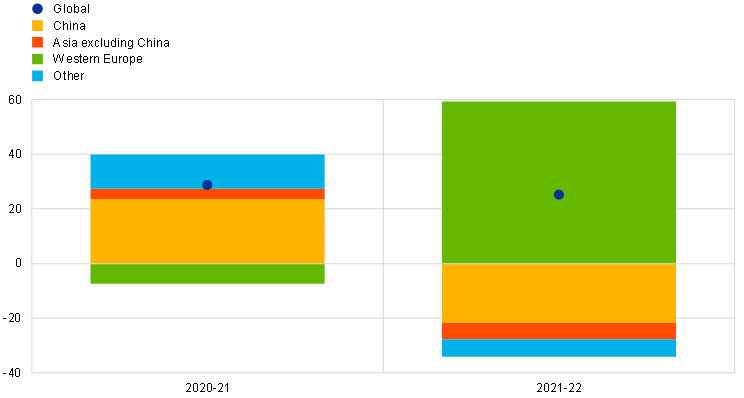
Note: In panel b, “Western Europe” includes Belgium, Finland, France, Gibraltar, Greece, Italy, Malta, the Netherlands, Norway, Portugal, Spain, Sweden, and the United Kingdom.
The risks of a rebound in Chinese energy demand and a complete cessation of Russian gas exports to the EU are highlighted by two illustrative scenarios for 2023. On the supply side, a favorable scenario assumes that Russian gas supplies to the EU remain at current levels. Because Russian gas supplies are significantly reduced in 2022, Russia would deliver on average about 40 bcm less gas in 2023 than in 2022. It is also assumed that most of the expansion of global LNG capacity in 2023 will be ensured by the EU . An adverse scenario assumes no Russian pipeline gas supplies to the EU and a recovery in Chinese energy demand, limiting the EU’s ability to secure additional LNG imports. On the demand side, both scenarios assume that the current EU-wide gas-saving measures, which are currently only in place until March 2023, will be extended until the end of 2023. It is also assumed that the EU will continue to need gas supplies before the winter of up to 90% must be filled.[4]
The security of gas supply in the EU remains vulnerable to global supply risks and changes in demand (Graph C). In the favorable scenario, the EU natural gas market would be largely in balance, while in the unfavorable scenario, the gas shortage could account for about 9% of annual gas consumption in the EU. The shortfall could drop to 4% if China’s LNG demand remains unchanged at 2022 levels, or to 2% if risks to Russian gas exports materialize. Such a shortfall can probably be closed by replacing gas with other energy sources, increasing energy efficiency and conducting a moderate depletion of stocks.[5] Nevertheless, in 2023 the EU’s gas security would remain vulnerable to further gas supply disruptions or shifts in demand. While the EU has significantly reduced its dependence on Russian gas, it has become much more sensitive to fluctuations in energy demand from the rest of the world, especially China.
Chart C
Two possible routes for the shortage of natural gas in the EU
(percentages of expected consumption in 2023)
Sources: Eurostat, Refinitiv and ECB staff calculations.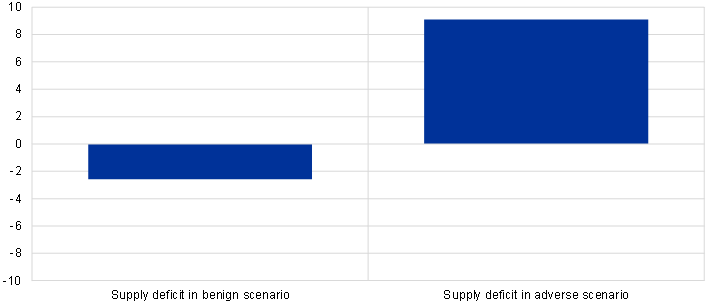
Explanation: Assumptions regarding gas consumption, production, exports and imports are based on recent developments, the EU gas savings plan and the EU gas storage target for the end of October 2023.
The challenge for the EU to ensure sufficient gas supply in 2023 will also depend on the weather and the depletion of gas supplies in the remaining part of the winter of 2022-23. EU Member States saved more gas in the winter of 2022-23 than foreseen in the EU gas savings plan, partly due to relatively warm temperatures. As a result, gas storage levels have remained high and the gas supply outlook has improved compared to expectations before the heating season began. However, if temperatures drop sharply in the coming months or if there is a prolonged cold spell, gas stocks could be depleted faster than assumed in our analysis, leaving EU gas markets in a more vulnerable position. At the same time, warm temperatures during the winter months could put the EU in a stronger position to meet the challenges in 2023, while high temperatures in the summer months would increase the demand for gas for electricity generation due to a greater need for air conditioning.
|
Sources 2/ https://www.ecb.europa.eu/pub/economic-bulletin/focus/2023/html/ecb.ebbox202301_01~6395aa7fc0.en.html The mention sources can contact us to remove/changing this article |
[ad_2]