
[ad_1]
Total debt balances rose $148 billion in the first quarter of 2023, a modest increase after record growth in 2022. Mortgages, the largest form of household debt, grew by just $121 billion, according to the latest Quarterly report on household debt and credit from the New York FBI Center for Microeconomic Data. The increase was tempered by a sharp decline in both the purchase and refinancing of mortgages. The pandemic boom in new purchases was driven by many factors: low mortgage rates, strong household balance sheets and increased demand for housing. Homeowners who refinanced in 2020 and 2021 benefited from historically low interest rates and will enjoy low borrowing costs for decades to come. borrowers extracted equity from their real estate assets, making more cash available for consumption. Here we examine the 2020-21 refi boom who refinanced, who took out cash, and how much potential consumption support these transactions generated. In this analysis, as well as the Quarterly reportwe use our Consumer Credit Panel (CCP)which is based on anonymized Equifax credit reports.
The refinancing boom
In the chart below, we split the volume of mortgage productions into purchase and refinancing mortgages. The refinancing boom due to COVID, which we observe from the second quarter of 2020 through the fourth quarter of 2021, was driven by a decline in mortgage interest rates of almost 200 basis points from November 2018 to November 2020. The refinancing boom in 2003 was similarly boosted by a decline of about 200 basis points, just like the mini boom in 2013. But there are at least three features that distinguish the recent boom in refinancing from previous ones. First, interest rates were historically low in the 2020-2021 pandemic years; many homeowners took advantage of these low rates by withdrawing equity, reducing monthly payments, or shortening installments. Second, the recovery in mortgage rates after reaching this low was historically strong. This quickly ended the wave of refinancing. Finally, equity was at an all-time high leading up to the pandemic, and as home prices continued to rise, many borrowers had excess equity to tap into.
About a third of outstanding mortgages were refinanced during the seven quarters of the refi boom, and another 17 percent of outstanding mortgages were refreshed through home sales during a time of high ask for housing. Subsequently, rates increased by 400 basis points from a historic low contract rate of 2.68 percent on 30-year mortgages in December 2020 to 6.90 percent in October 2022, a swing of a magnitude not seen since the early 1980s. has not been seen again, according to Freddie Macs Primary Mortgage Market Questionnaire. In the first quarter of 2023, it was more difficult to find incentives for refinancing and the refinancing rate dropped to near an all-time low, as shown by the red line in the chart below.
Mortgage production is tapering
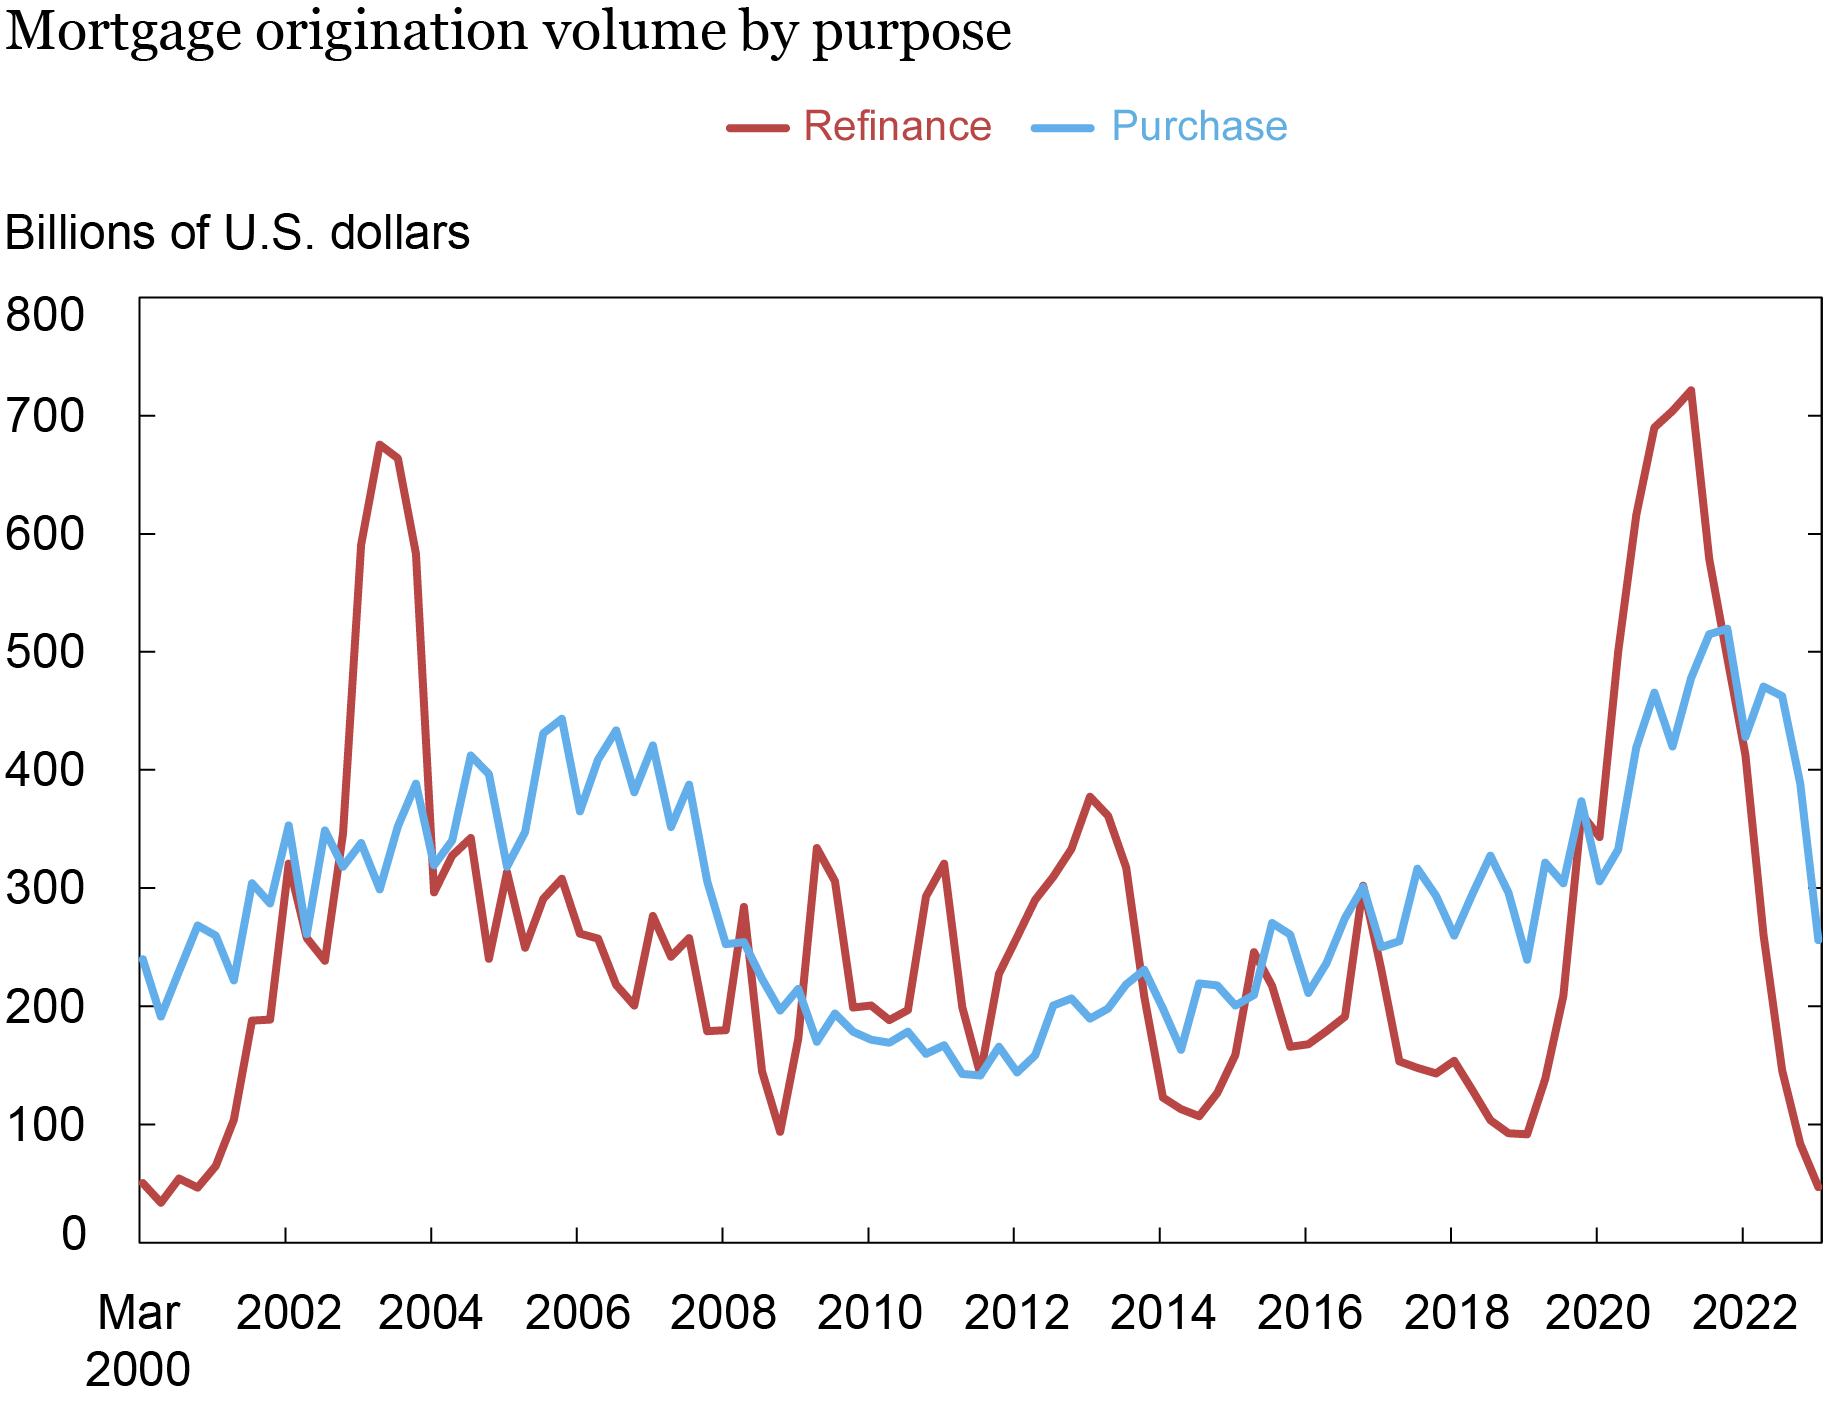
Notes: Due to credit reporting delays, originals may be registered 6 to 8 weeks later. Balances are in nominal dollars.
Cash Out or Cash Flow?
In the chart below, we plot the present value of the extraction of nominal equity over time. We estimate that between the second quarter of 2020 and the fourth quarter of 2021, $430 billion in home equity was obtained through mortgage refinancing, as shown in the chart below. The pace of equity withdrawals came to a screeching halt as mortgage rates began to rise and quarterly equity withdrawal volumes were near historic lows in the first quarter of 2023, especially as a percentage of disposable personal income, as shown by the red line below. That line also shows that while the recent pick-up in the payout is noticeable, as a share of income it’s nowhere near as significant as the 2002-2005 refi boom.
Home Equity Extraction During Pandemic Refi Boom
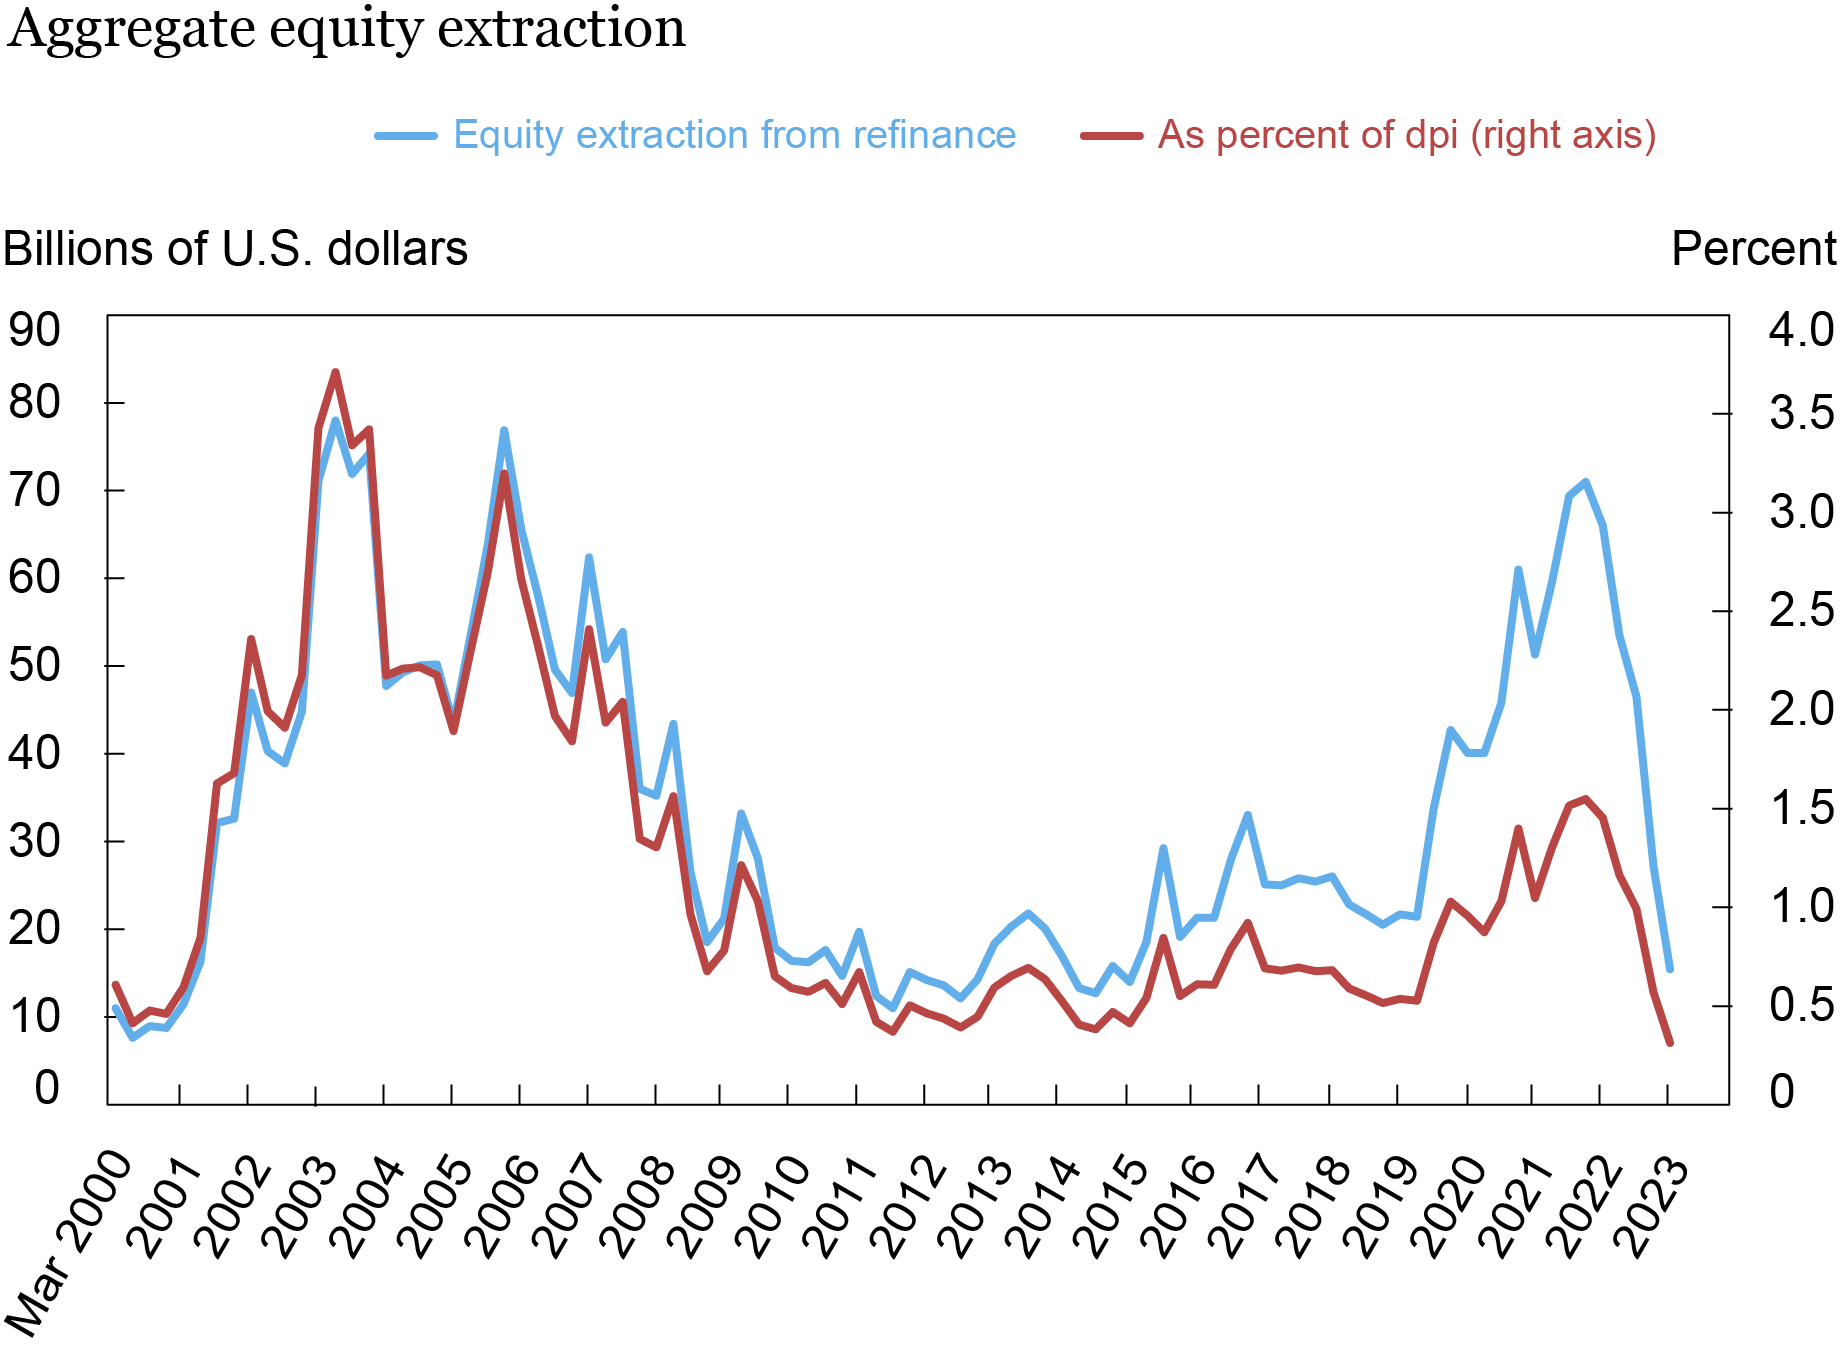
During the seven quarters, approximately 14 million mortgages were refinanced, 64 percent of which were interest rate refinances, which we classify here as those with a balance increase of less than 5 percent of the loan amount. For the rate refinancers, the average monthly payment decreased by $220. For disbursed refinancers, the average amount paid out was $82,000 and the average monthly payment increased by $150.
Who refinanced?
Next, we look at some key features of the mortgages that were refinanced during the pandemic.
We first look at the term of the loan and the balance of the outstanding pool of mortgages. Older vintage mortgages that originated before 2010 were the least likely to refinance. In fact, less than 9 percent of mortgages taken out before 2010 and still due in 2020 were refinanced. About 17 percent of mortgages taken out between 2010 and 2014 were refinanced. By contrast, nearly a third of mortgages from 2015 and later were refinanced in the relevant quarters.
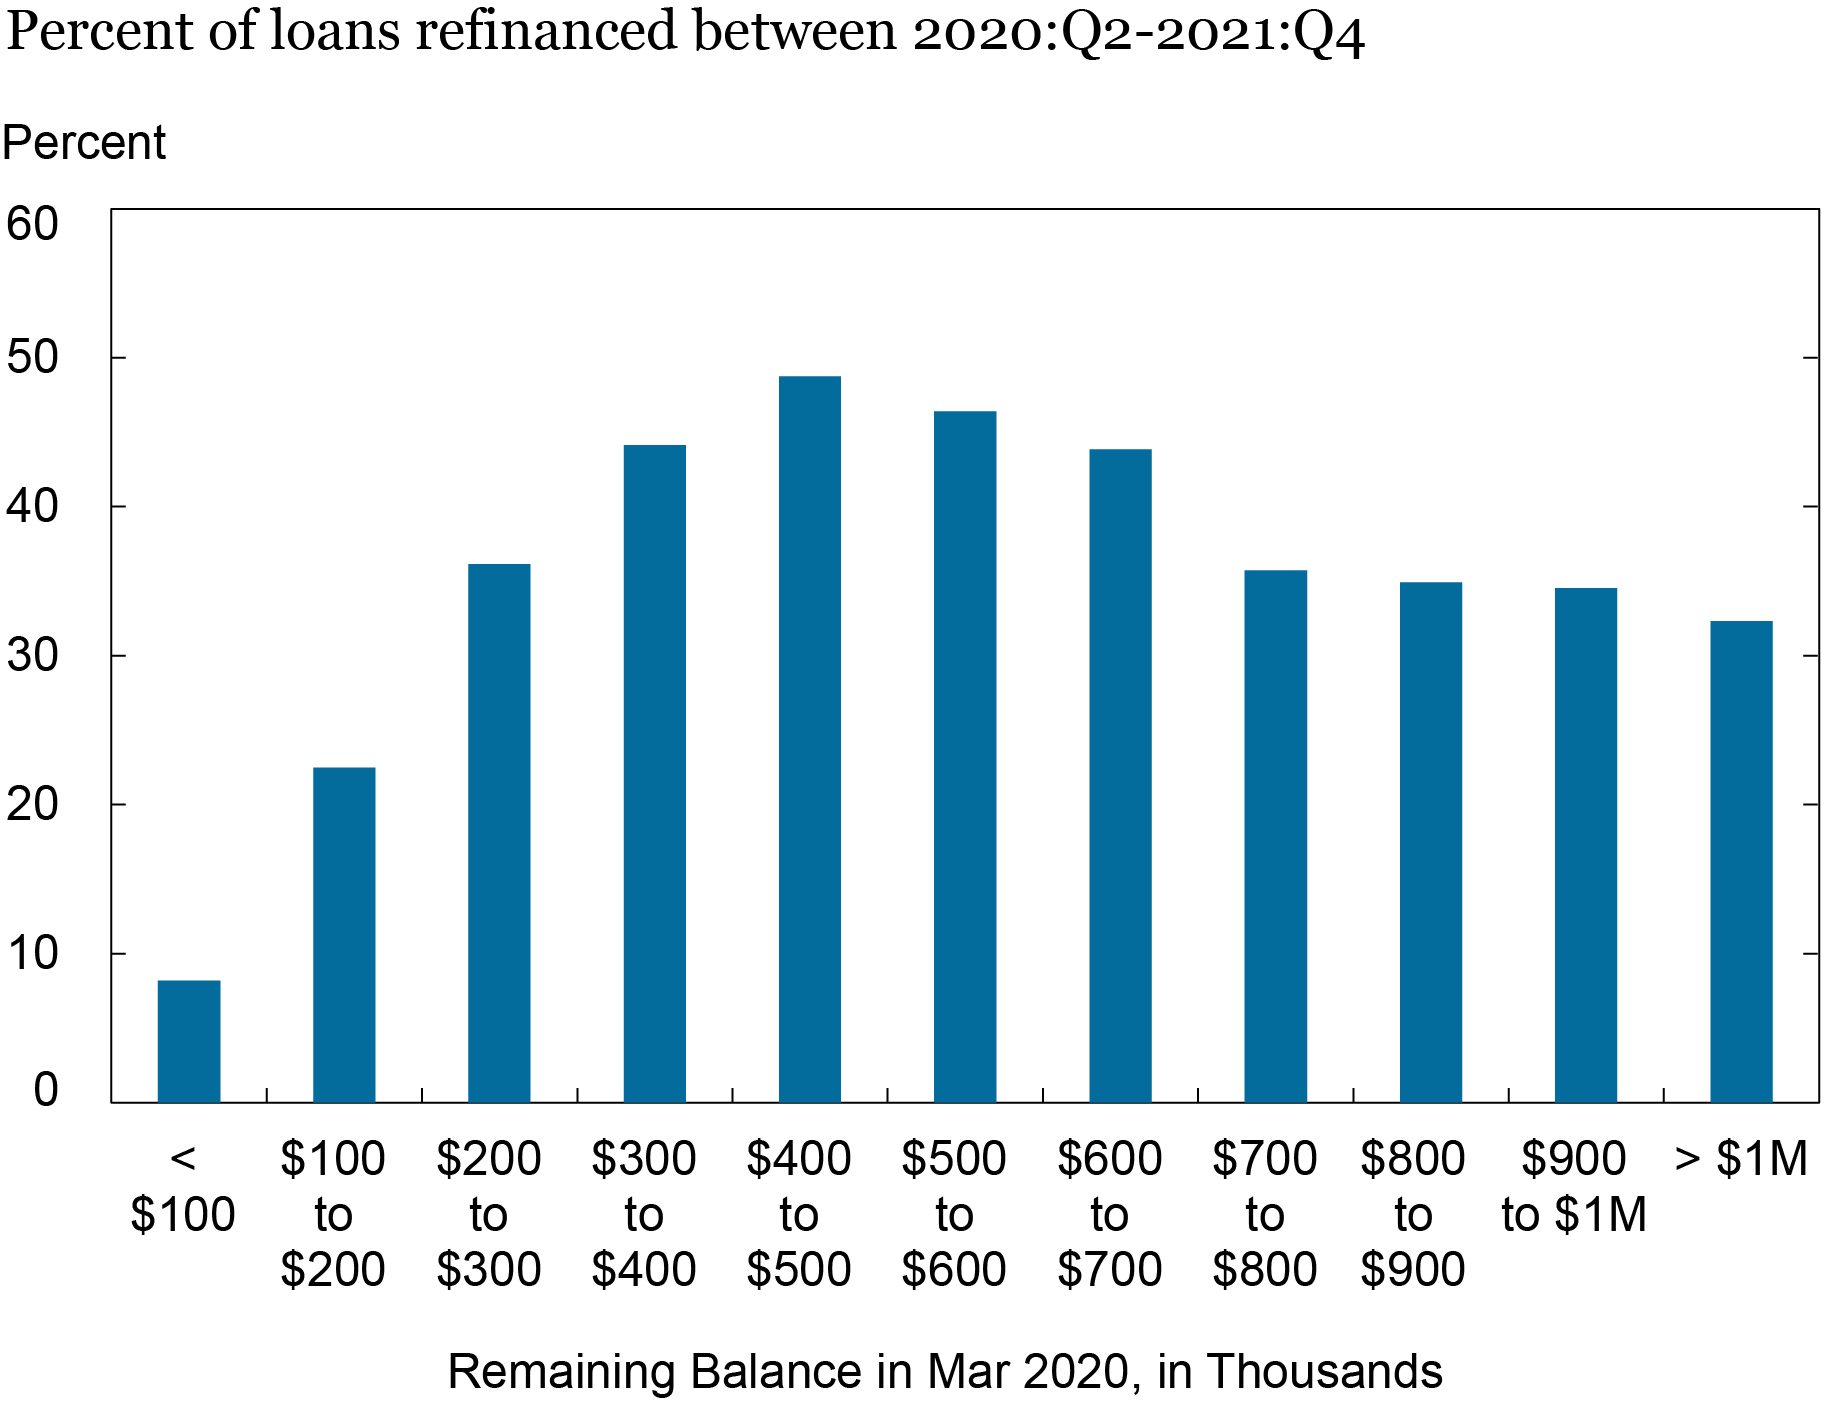
We expect a correlation between the remaining balance of mortgages and the propensity to refinance. It would make more sense to refinance if the balance is higher, since the profit from refinancing is proportional to the refinanced balance. This is indeed what we illustrate in the chart below. Less than 10 percent of mortgages with outstanding balances of less than $100,000 as of Q1 2020 were subsequently refinanced, compared to nearly half of mortgages with balances between $400,000 and $500,000. Interestingly, the tendency starts to decrease after $500,000.
Mortgages with a smaller balance were refinanced less quickly
In terms of investor type of mortgages, we see that 25 percent of GSE mortgages were refinanced – an identical share between Fannie Mae and Freddie Mac. This similarity is perhaps unsurprising given the possible substitution of command between GSEs. FHA borrowers were less likely to refinance at 22 percent, despite the availability of FHA’s streamlined refinance program. The most likely refinancing was VA mortgages. About 38 percent of VA mortgage accounts outstanding as of the first quarter of 2020 had been refinanced by the end of 2021. The percentage of total balances refinanced is higher as higher balance mortgages are more likely to be refinanced as shown above. About 35 percent of balances for GSE mortgages, 29 percent for FHA mortgages, 46 percent for VA mortgages, and 29 percent for other types were refinanced during this period.
Conclusion
Ultimately, fourteen million mortgages were refinanced during the COVID refinancing boom, and these refinancings will impact the mortgage market for years to come. Many borrowers who refinanced during the boom have either improved their cash flow through a reduction in payments on their existing properties, or increased their liquidity by taking equity out of those properties. About five million borrowers raised a total of $430 billion in home equity from their refinances. Meanwhile, nine million people refinanced their loans without withdrawing equity and reduced their monthly payments, resulting in a total $24 billion a year reduction in their annual housing costs. The end of the most recent period of exceptionally low interest rates has somewhat discouraged homeowners from selling or changing properties: owners looking to move now will face higher borrowing costs and higher prices, with current house prices more than 36 percent higher than before -pandemic. The improved cash flow generated by the recent refinancing boom may provide important support for future consumption.

Andrew F. Haughwout is the Director of Household and Public Policy Research in the Research and Statistics Group of the Federal Reserve Bank of New York.

Donghon Lee is an economic research advisor in Consumer Behavior Studies at the Research and Statistics Group of the Federal Reserve Bank of New York.

Daniel Mangrom is a research economist in Equitable Growth Studies at the Research and Statistics Group of the Federal Reserve Bank of New York.

Joelle Scally is a senior data strategist at the Research and Statistics Group of the Federal Reserve Bank of New York.
Wilbert van der Klaauw is the economic research advisor for household and public policy research at the Research and Statistics Group of the Federal Reserve Bank of New York.
How to quote this message:
Andrew Haughwout, Donghoon Lee, Daniel Mangrum, Joelle Scally and Wilbert van der Klaauw, “The Great Pandemic Mortgage Refinance Boom”, Federal Reserve Bank of New York Liberty Street EconomyMay 15, 2023, https://libertystreeteconomics.newyorkfed.org/2023/05/the-great-pandemic-mortgage-refinance-boom/.
disclaimer
The views expressed in this release are those of the author(s) and do not necessarily reflect the views of the Federal Reserve Bank of New York or the Federal Reserve System. Any errors or omissions are the responsibility of the author(s).
|
Sources 2/ https://libertystreeteconomics.newyorkfed.org/2023/05/the-great-pandemic-mortgage-refinance-boom/ The mention sources can contact us to remove/changing this article |
[ad_2]