
[ad_1]
champion
“A ship is safe in port, but that’s not what ships are for.” John A. Shedd
In early June, I noted on Twitter and here on Seeking Alpha that the relative weakness of the defensive sector seemed to be continuing capitulation, and that the sell-off would likely end around mid-June, bringing in another high-risk period for equities. Of course, none of that happened as June progressed, and the risk triggers in The Lead-Lag Report remained risk-on, and remained so throughout the month. But despite this, I still believe that you have to be careful here, like the reasons I gave then largely remain in place.
Industry weakness
The rate at which defensive sectors such as Utilities (XLU), Consumer Staples (XLP), and Healthcare (XLV) underperformed the broader S&P 500 (SPY) was incredible. Why is this important? Because low beta defensive sectors tend to outperform high volatility regimes. It is clear that utilities in particular have done the exact opposite, which is again IS risky behavior. But the collapse makes it more likely to bottom out and bounce back, suggesting a correction is not far off.
The ratio is pushing to the lows of 2021 – when the stock bear market began.
TradingView.com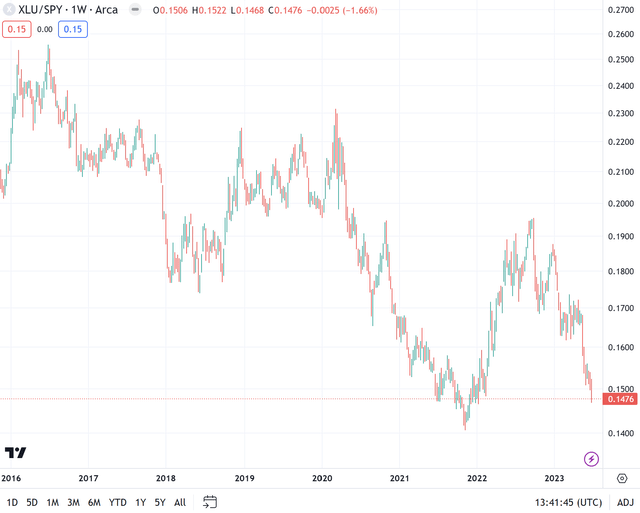
The melt-up in perspective
A melt-up is a sudden increase in investment performance, often driven more by investor sentiment than actual economic improvements. While this phenomenon can lead to significant short-term gains, it can also pose a risk to investors, as the rapid rise in share prices is often unsustainable in the long run.
Melt-ups end when everyone believes in them.
The narrow market and AI story
While technology (XLK) and artificial intelligence stocks like Nvidia (NVDA) have performed exceptionally well, it’s important to note that this has been a small market. Small cap stocks, consumer discretionary and retailers (XRT) performed relatively poorly. The story of a large-cap to small-cap rotation in early June completely failed as the small-cap (IWM) to large-cap (SPY) ratio reached new relative lows.
Tradingview.com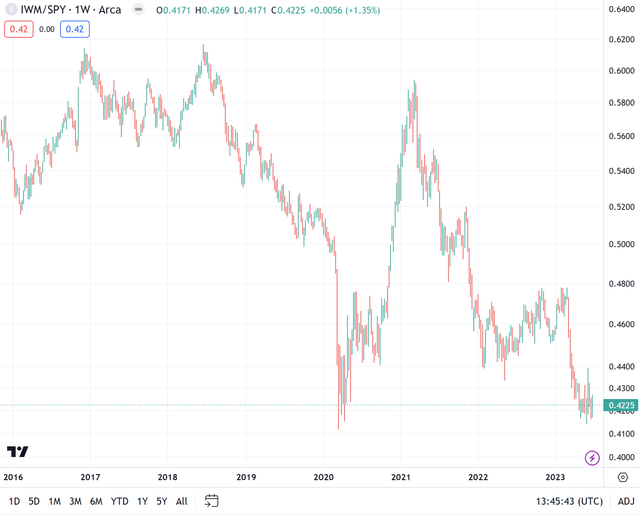
The role of VIX in market analysis
The S&P VIX index, also referred to as the ‘fear gauge’, is a valuable tool for assessing market expectations regarding short-term volatility. A low VIX level usually signifies a period of relative calm and stability in the markets, but can also be interpreted as a warning sign of possible sudden and sharp market movements. The VIX (VIXY) crush may persist and, as we’ve seen in market history, go even lower. All that means is that we’ve reached a point of bull overconfidence, which may be justified, but probably not because, simply put, that’s how markets work.
Conclusion: only the timing has changed
The current market conditions warrant a careful and proactive approach. The time to worry is when no one really cares. As defensive sectors continue to capitulate, investors may need to reevaluate how long bullish optimism is warranted. I am skeptical that it can go much longer, as examples from 1987 show us. Low VIX levels are necessary for high VIX levels.
 Anticipate crashes, corrections and bear markets
Tired of being a passive investor and ready to take control of your financial future? Introducing The Lead-Lag Report, an award-winning research tool designed to give you a competitive edge.
The Lead-Lag Report is your daily resource for identifying risk triggers, uncovering high-yield ideas, and gaining valuable macro observations. Stay ahead with critical insights into leaders, laggards, and everything in between.
Go from risk-on to risk-off with ease and confidence. Subscribe to The Lead-Lag Report today.
Click here to access and try the Lead-Lag Report FREE for 14 days.
|
Sources 2/ https://seekingalpha.com/article/4614966-stock-market-correction-delayed-but-not-for-much-longer The mention sources can contact us to remove/changing this article |
[ad_2]