
[ad_1]
The new, rapidly spreading B.1.1.529 strain of coronavirus declared a variant of care by the World Health Organization ravaged global markets on Black Friday, raising concerns about how the economy and Wall Street might perform in the coming week after a sell-off that wiped out November’s gains for the S&P 500 index SPX,
and the Nasdaq Composite COMP,
and sent the Dow Jones Industrial Average DJIA,
the most in one day since October 28, 2020.
The WHO said the omicron variant, which has been detected in Belgium, Israel and Hong Kong and first identified in southern parts of Africa, is more transmissible than the delta strain that is currently dominant worldwide, and other variants.
The emergence of the new species led to the White House announcement of restrictions, starting Monday, on travel for non-US citizens and residents from South Africa, as well as from Botswana, Zimbabwe, Namibia, Lesotho, Eswatini, Mozambique and Malawi, joining the European Union, the UK, Singapore and Japan, who have also announced similar travel bans.
The market sell-off during the abbreviated Black Friday session and the commensurate flight to assets that investors hope will outperform amid new mobility restrictions helped overshadow the usual focus on retail on a day that saw heavy consumer spending prior to the Christmas holidays. Friday’s downturn also provided a crystal clear reminder that the path of the market and economy depends on the course of COVID.
What is not clear is whether the latest development of the coronavirus will cause lasting damage to the complexion of the market. Omicron comes at a fragile time for optimistic investors, with bears pointing to high stock valuations, inflation worries and concerns about global economic growth as reasons to expect a decline in stocks falling from a more than 5% peak know how to avoid.
In theory, the Friday after Thanksgiving environment is traditionally lightly traded and therefore more prone to excessive price swings.
The Nasdaq saw its lowest volume of the year on Black Friday, with 3.479 billion stock trading hands, well below the year-to-date average of 5.099 billion. The total compound volume, including trading on Intercontinental Exchange ICE,
NYSE-owned platforms totaled $8.760 billion, compared with a year-to-date average of $11.196 billion, according to Dow Jones Market Data.
Still, only time will tell if the response to omicron is a textbook, spontaneous sell-out, or something more sinister.
MarketWatchs Bill Watts wrote, citing Friday’s research by Mark Arbeter of Arbeter Investments, that the next level of support for the S&P 500 after closing at 4,594.62 on Friday is 4,570, the 50-day exponential average; 4,566, the 38.2% retracement of the rally; and 4,550, an earlier high from early September.
It’s too early to know how much the new variant will affect economies and markets, and Friday’s market moves are likely exacerbated by reduced liquidity over the US Thanksgiving holiday and the risk of further bad news over the weekend. , writes Jonas Goltermann senior markets economist at Capital Economics, in a research paper Friday.
JC Parets of the All Star Charts blog writes that things could get tricky if the S&P 500 moves below 4,500, with little support below that point.
You know that parents always tell you that nothing good ever happens after midnight? Well, nothing good happens in the S&P 500 below 4500, he writes in a Friday blog.
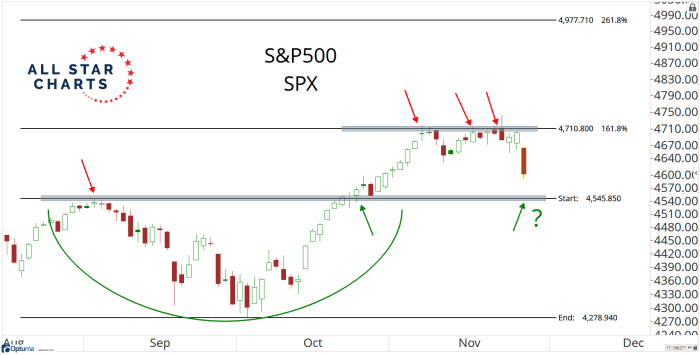
All star maps
If that were lower, there is likely a much bigger problem and the heaviest cash positions in 18 months would be justified, Parets writes.
Some analysts say there are legitimate reasons for public health unease.
The fact that this variant seems to be spreading much faster than previous versions (including the Delta variant) should be monitored very closely, Michael Strobaek, global chief investment officer at Credit Suisse, wrote in a research note. There are some questions about the effectiveness of existing Pfizer PFE COVID vaccines,
and Moderna MRNA,
due to the number of mutations the omicron variant carries on the spike protein. The spike protein is the part of the virus that is targeted by COVID-19 vaccines.
Jefferies analyst led by analyst Sean Darby notes that risk appetite was already declining before Black Friday and the sell-off may have been a tipping point in favor of caution and risk moderation.
The news of a new or not so new COVID variant spreading in Southern Africa
appears to have been the tipping point in changing risk appetite in the past 24 hours, the Jefferies analyst wrote.
However, in the past month there has been a reversal in risk variables and
increasing number of tailed treasury auctions, decreasing stock market width and
the imperceptible change in US retail appetite that seems to have gone unnoticed.
According to Darby and his colleagues, positioning in global equities is one of the most aggressive in US history.
Jefferies research suggests investors now expect the Federal Reserve, under chairman-designate Jerome Powell, to accelerate the pace of phasing out central bank asset purchases, leading to tighter financial conditions that could prove unfavorable for risky assets. Goldman Sachs sees the Fed ramping up to $30 billion a month from a $15 billion cut, and estimates three key rate hikes in 2022, up from two.
Ultimately, the Sharpe ratio is a measure of return per unit of risk
run for global equities. We expect the gap between the performance of risky assets and safe-haven assets to narrow, Jefferies wrote.
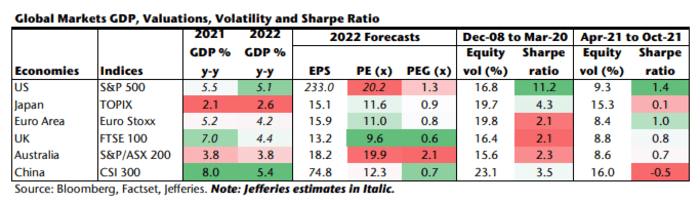
via Jefferies
However, the situation could still be a buying opportunity for daring investors.
Strobaek wrote that risky assets like stocks are likely to return some strength, but we would see this as an opportunity in selective and specific areas.
At this point, we’re reiterating our assessment from the latest Investment Committee report that we keep equities a small overweight in portfolios and government bonds an underweight, writes the CIO of Credit Suisse.
Analysts at Citigroup also said we would accept any dip, noting that the bearish checklist shows no significant red flags. Valuations look stretched, but other factors (credit spreads, fund flows) aren’t particularly extensive yet, Citi writes, with 7.5 out of 18 red flags in its readings of global markets, while the US is 9.5 out of 18 sees.
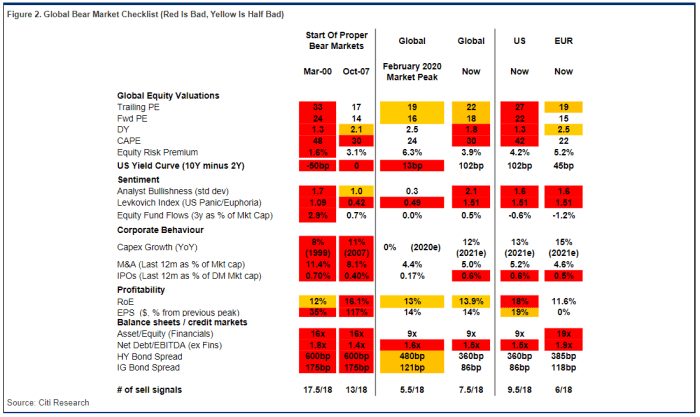
Citi Research
Greg Bassuk, CEO of AXS Investments in Port Chester, NY, says the week-end sale may have sparked a Black Friday sale for stock market investors.
Black Friday is typically the unofficial kick-off to the annual Christmas shopping season. But we believe the real shopping is for stocks that have been beaten by Covid infection spikes, inflation fears and supply chain problems, but still have strong fundamentals that will boost their profits when the economy eventually reopens, he wrote.
That said, some analysts note that the lockdowns in Europe and the spread of COVID, even before the ommicron declaration, were reasons for caution as they will affect the global growth outlook.
Either way, it looks like some warning could be in place next week and color trading for the rest of 2021.
Trading on Monday will help determine if the bullishness continues or if a bearish phase is crystallizing.
It will be a week focused on the employment situation, with the November US jobs report expected late this week and Powell and others giving their final thoughts before a media blackout begins ahead of the final meeting of the Federal Open. Market Committees of 2021 on December 14-15.
See: Fed inflation concerns at last meeting left room for an accelerated tapering of bond purchases
Santa Claus meeting, anyone?
What’s on the economic calendar?
Monday
A Report on Pending Home Sales at 10 a.m. Eastern Time
Tuesday
-
S&P Case-Shiller House Price Index for September at 9:00am
-
Chicago Purchasing Managers Index for November at 9:45 AM
-
Consumer confidence index for November at 10 a.m.
Wednesday
-
November ADP Employment Report at 8:15am
-
IHS Markit purchasing managers index finally read at 9.45 am
-
November ISM Manufacturing Index at 10am
-
Construction releases for October at 10 a.m.
-
Beige Book at 2pm
Thursday
Weekly jobless claims report for the period ending November 27 at 8:30 a.m.
Friday
-
November Nonfarm Payrolls at 8:30am
-
IHS Markit non-manufacturing lecture for November at 9.45am
-
November ISM Service Report at 10am
-
October factory orders at 10 a.m.
-
Core Capital Goods Orders Updated for October at 10am
Powered speakers
Monday
-
Fed Chairman Jerome Powell delivers opening speech at 3:05 p.m. ET at the Introducing the New York Innovation Center event.
-
Fed Government Michelle Bowman lectures at a virtual symposium on Indigenous economies hosted by the Bank of Canada, Tulo Center of Indigenous Economics and the Reserve Bank of New Zealand at 5:05 PM
Tuesday
-
Powell will testify before the US Senate Banking Committee with the Secretary of the Treasury at 10 a.m Janet Yellen, on the state of the US economy during the COVID pandemic as part of the Cares Act.
-
Outgoing Fed Vice Chairman Richard Clarida speaks at 1 p.m. at an event hosted by the Federal Bank of Cleveland.
Wednesday
Outgoing Fed Government Randal Quarles will offer parting thoughts at an American Enterprise Institute at 11 a.m.
|
Sources 2/ https://www.marketwatch.com/story/heres-what-the-black-friday-carnage-may-mean-for-the-stock-markets-trade-monday-analysts-say-11638021516 The mention sources can contact us to remove/changing this article |
[ad_2]